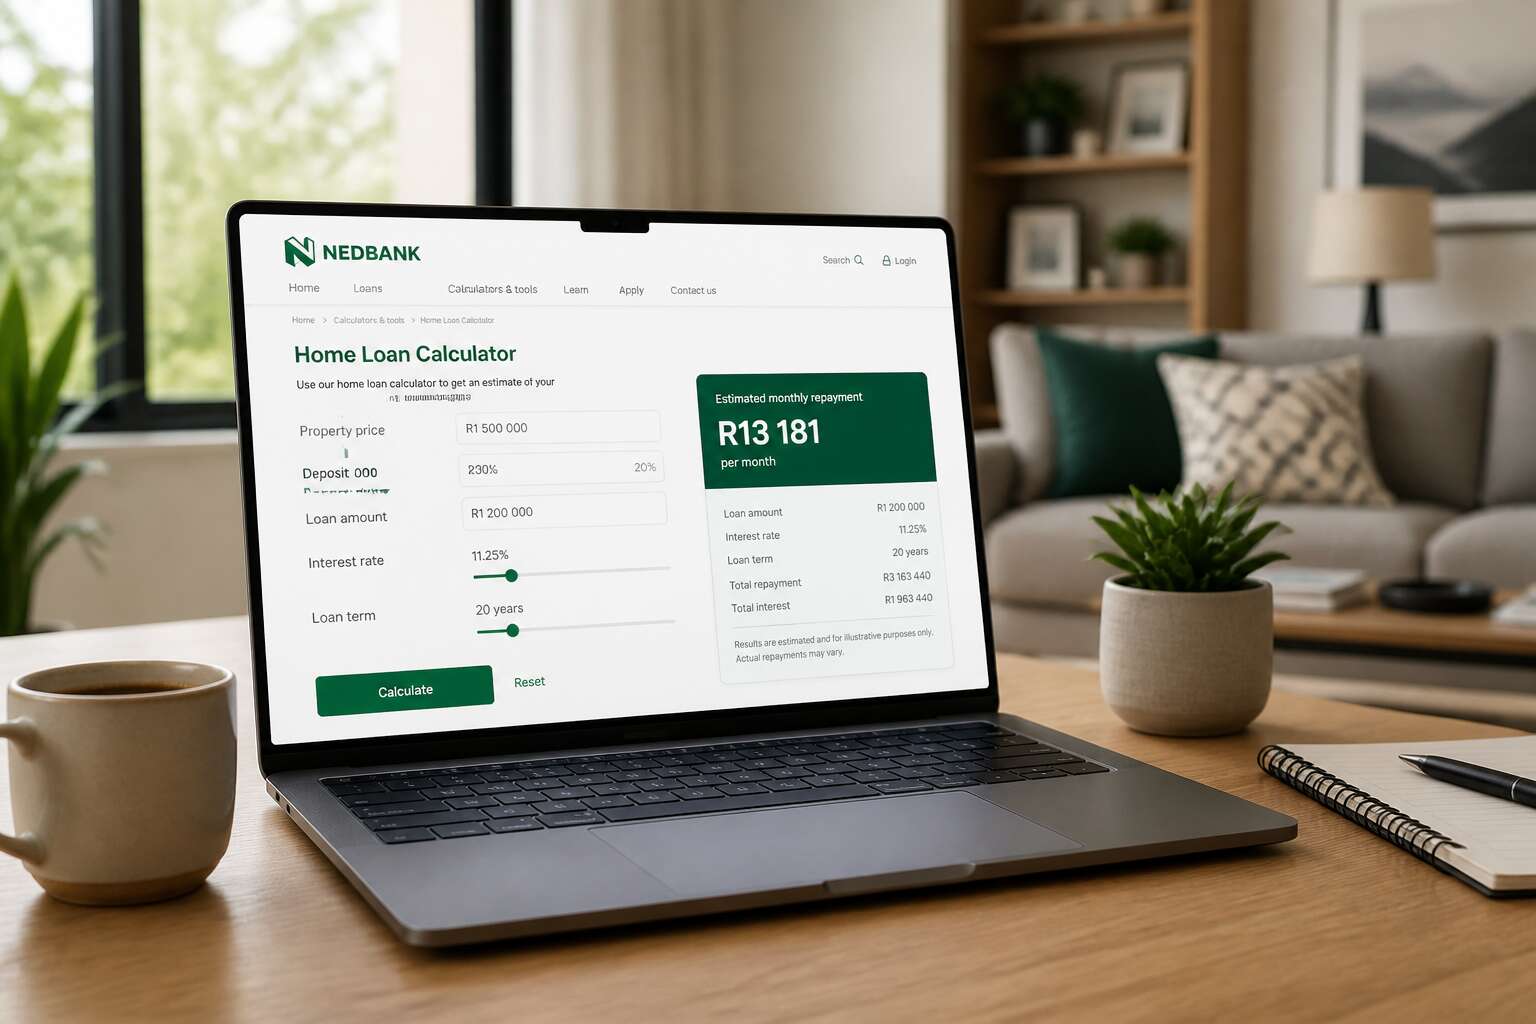
Estimate repayments with the nedbank home loans calculator.
Understanding the Nedbank Home Loan Calculator
How the Calculator Works
A single missed bond payment costs more than interest. The nedbank home loans calculator exists to prevent that. It translates your income, expenses, and deposit into a borrowing figure with unsettling precision. You enter your gross salary, monthly debt obligations, and the property price. The tool then simulates interest rates across various terms, exposing the monthly repayment before you commit emotionally or financially.
Here is what the calculator quietly considers:
– your age and employment type, which many applicants ignore
– the loan-to-value ratio, which affects your interest rate offer
– the bond initiation and legal fees, which alter your total cash need
Adjust the deposit amount, and you will see affordability shift in real time. That iterative process reveals what a bank likely approves, not what you hope to borrow. It turns guesswork into a clear negotiation starting point.
How to Interpret Your Results
The nedbank home loans calculator gives you a number, but the real value lies in reading what that number represents. It is not a simple affordability figure. The result is a composite of your financial profile, market conditions, and the bank’s risk appetite. A lower monthly repayment than you expected could indicate a favourable interest rate offer, not just a longer loan term. Conversely, a higher figure may signal that your loan-to-value ratio is working against you, a detail many applicants overlook.
When you receive your results, consider these components:
– The interest rate assumption used in the calculation
– The total interest payable over the loan’s lifetime
– The portion of your gross salary that the repayment consumes
The true insight emerges when you compare these figures against your actual budget. If the calculator suggests a repayment that consumes more than 30% of your net income, you have a red flag. The nedbank home loans calculator is a mirror, reflecting what the bank will likely offer. Your interpretation of that reflection determines whether you walk into a branch prepared or leave disappointed. The output is a starting point, not a verdict. Use it to refine your deposit strategy or adjust your property expectations before you engage with a consultant.
Step-by-Step Guide to Using the Online Tool
Accessing the Calculator on the Nedbank Website
Locating the nedbank home loans calculator takes less than a minute. Open your browser and navigate to nedbank.co.za. From the menu, select ‘Borrow’, then ‘Home Loans’. You will find the calculator on the right hand side of the page, ready to use.
Once you click the tool, it loads directly in your browser. No downloads, no login required. The screen presents three empty fields: property price, deposit amount, and loan term.
1. Type the purchase price into the first field.
2. Enter the deposit you plan to contribute.
3. Select the repayment period in years.
The nedbank home loans calculator updates your estimated monthly instalment the moment you finish. Adjust the figures as often as you wish. The interface responds without refreshing the page, which makes comparing different scenarios straightforward. If you want to view offers from multiple banks, a bond origination option sits just below the results.
Entering Your Financial Details Accurately
Using the calculator properly begins with honest input. Your property price must reflect the actual purchase amount, not a hopeful estimate. Similarly, the deposit field should represent what you truly have saved, including any gifts or proceeds from a sale.
Follow these steps to avoid common errors:
- Enter the full purchase price as per the offer to purchase.
- Type your deposit exactly as you will pay it.
- Choose a term that matches your budget, not your ideal.
After each entry, pause. The nedbank home loans calculator calculates monthly instalments based on your figures. If you change one field, the result shifts instantly. That is why accuracy matters. A deposit figure that excludes bond costs or transfer fees will mislead you. The calculator assumes only what you type, nothing more.
Adjusting the Deposit and Repayment Period
Once your base figures are in, the real work begins. The deposit and repayment period are the two figures that shape your monthly commitment. Slide the deposit upward, even modestly, and the nedbank home loans calculator responds with a lower instalment.
Adjusting the repayment period takes equal care. A longer term spreads the cost but adds interest. A shorter term does the opposite. I move the term slider a few months at a time, because small changes reveal the true cost of borrowing.
When you adjust these fields, keep a simple rhythm:
- Change one variable at a time so the result stays readable.
- Watch the total interest, not just the monthly payment.
- Try a few combinations to see how deposit and term interact.
The nedbank home loans calculator rewards this experimentation with a clear view of what fits your budget.
Understanding the Affordability Assessment
The affordability assessment is the part of the nedbank home loans calculator that most buyers skip, which is a mistake. It converts your income and existing debt into a maximum bond amount. The tool does this in seconds, but the output only makes sense when you understand what the bank is actually examining.
Working through the steps takes a clear sequence:
1. Enter gross income before deductions.
2. Add monthly obligations such as car payments and store accounts.
3. Confirm the deposit amount you have genuinely saved.
4. Read the assessed amount rather than the advertised rate.
The nedbank home loans calculator then weighs your numbers against the bank’s lending criteria. It reveals what you qualify for, and that often differs from what you wanted. A lower assessed figure may feel disappointing, but it prevents future financial strain. Keep your expenses honest, and the assessment becomes a genuinely useful view of your position.
Factors That Influence Your Home Loan Repayments
Interest Rates and the Prime Rate
In South Africa, the interest rate attached to your bond is rarely a static figure. It is a volatile number, tethered to the broader economic currents and the South African Reserve Bank’s monetary policy decisions. When the Reserve Bank adjusts the repo rate, the prime rate follows suit, and this directly impacts your monthly obligation. The difference between a 10% and an 11.5% prime rate on a 20 year bond can translate into thousands of rands over the life of the loan, a reality that the nedbank home loans calculator can illuminate with stark clarity.
Several personal factors also sway the interest rate you are offered. Lenders assess your credit score as a measure of your historical reliability. They scrutinise your debt-to-income ratio to see if you are overextended. Even the size of your deposit plays a pivotal role; a larger upfront payment reduces the lender’s risk, often securing a more favourable rate.
– Your credit history and score
– The loan amount relative to the property value
– The stability of your employment and income
A variable rate means your repayments will fluctuate with the prime rate, which requires a degree of financial agility. The nedbank home loans calculator uses the current prime rate to give you a realistic projection, but it is wise to consider how a 1% increase would alter your budget. This tool allows you to manually adjust the interest rate to stress test your finances against future hikes, offering a sobering glimpse into potential scenarios. Understanding this dynamic is essential for long term financial planning, as the rate you secure today is not necessarily the rate you will pay tomorrow.
Loan Term and Repayment Period
The length of your mortgage is a lever you pull with your eyes half closed. Extend the repayments and the monthly figure drops, but the total interest compounds into a staggering sum. Shorten the term and you accept a heavier monthly load to shed decades of future debt. I’ve watched too many buyers skip this calculation entirely. The nedbank home loans calculator reveals this arithmetic instantly! Punch in two different terms and watch the total repayment climb or fall. The nedbank home loans calculator’s real value lies in exposing the true cost of time. Common term lengths include 20, 25, and 30 years, each altering your cash flow and total interest in distinct ways:
- Monthly cash flow demands
- Total interest paid over the bond’s life
- How quickly you build equity
A shorter term accelerates equity growth but pressures your budget. A longer term does the reverse. Neither is universally correct.
Deposit Amount and Loan-to-Value Ratio
The size of your deposit does more than shrink the loan amount you request. It sets your loan-to-value ratio, or LTV, and that single number influences how much you repay each month. A larger deposit pushes your LTV lower, which signals lower risk to the bank. This often unlocks a more favorable interest rate. The nedbank home loans calculator accounts for this, but only if you enter the correct deposit figure.
Here is what your deposit and LTV directly affect:
– The interest rate the bank offers you
– The monthly repayment amount
– Whether you need to pay bond insurance
Bond insurance appears when your LTV climbs above 80 percent. That extra cost can add hundreds of rands to your monthly obligation. When you adjust the deposit in the nedbank home loans calculator, watch how the total repayment shifts. A modest increase in your deposit can reduce your LTV enough to change your entire bond structure. That is why entering an accurate, realistic deposit matters more than most buyers assume.
Your Credit Score and Financial Profile
Your credit score carries more weight than many buyers realise. It tells the bank how reliably you have repaid debt in the past, and it helps determine the interest rate attached to your bond. The nedbank home loans calculator uses this information to estimate your monthly repayment with a rate that fits your risk profile.
A clean credit record, steady income, and manageable existing debt all work in your favour. They signal stability. A history of missed payments or high outstanding balances can push your rate upward, which raises your monthly obligation.
The calculator does not judge you. It simply translates your financial profile into a number you can plan around.
Extra Payments and Early Settlement
The road to full ownership is rarely a straight line. For most South Africans, a home loan represents decades of commitment, and the true cost of that commitment extends beyond the initial approval letter. When you use the nedbank home loans calculator, you see a single number. That number, however, is not immutable. It shifts and responds to the financial choices you make long after the bond has been registered.
Fewer buyers realise that the trajectory of their debt is a living thing. By contributing an additional amount each month, you directly attack the capital balance. This reduces the interest that accrues over the remaining lifetime of the loan. The effect is exponential. Your monthly repayment remains the same, but the portion of it that reduces your principal grows incrementally. This results in a loan term that is shorter than you originally anticipated. For many, shaving off five or seven years of repayments is a more compelling target than a slightly lower interest rate.
Some bonds carry a penalty for early settlement, a relic of a time when banks guarded their interest income fiercely. Standard home loan products in South Africa largely allow for unlimited additional payments without penalty. This flexibility is a powerful tool. Consider the maths:
– An extra R500 per month on a 20-year bond of R1 million could reduce your interest cost by hundreds of thousands of Rands.
– Settling the bond in a lump sum, perhaps from an annual bonus, avoids the need to renegotiate your rate.
– The nedbank home loans calculator can be adjusted to model these additional payments, showing you the new settlement date.
These figures are not abstract. They represent the difference between holding a title deed in your golden years versus carrying debt into retirement. The freedom of early settlement is not about avoiding the obligation; it is about reclaiming the monthly cash flow for other purposes. The calculator serves as your guide, translating the desire to pay off your home faster into a concrete, actionable figure that you can track month by month.
Tips for Maximising Your Home Loan Approval Chances
Reviewing Your Credit Report Before Applying
Your credit report is the silent gatekeeper of your home loan application. Before you ever open the nedbank home loans calculator, that document has already started shaping your future. Pull it, scrutinise it, and challenge anything that looks unfamiliar.
Errors happen more often than people expect. A missed payment logged against the wrong account, an old judgement that should have fallen away, a credit limit that does not match reality. Each blemish chips away at your approval odds. Fixing them takes weeks, so start now, not on the day you apply.
Request your free credit check from a registered bureau and scan for red flags:
- Check every account listed belongs to you.
- Confirm your address and ID details match.
- Note any hard enquiries you did not initiate.
Once your report reads clean, your interest rate reflects the effort, and the nedbank home loans calculator shows numbers you can actually trust.
Reducing Your Debt-to-Income Ratio
Calculating what you can borrow is only half the story. Lenders measure your weight of debt against your income, a figure known as the debt-to-income ratio. A lower ratio signals you have room to breathe. It means you can absorb a bond repayment without buckling under existing pressures. The nedbank home loans calculator uses this ratio to determine how much risk you represent.
Reducing this ratio is a deliberate act, not a passive hope. You must shrink your monthly obligations before you approach the application. The most immediate lever is paying off revolving credit, especially store cards and credit cards. These are expensive debts that count heavily against you. Settling them frees up monthly cash flow which directly improves your standing.
– Settle small outstanding balances first to build momentum
– Avoid taking on new credit, including furniture financing or personal loans
– Pay more than the minimum amount on existing accounts each month
You can also increase your income to dilute the ratio. This could be a second stream of income, a side business, or a salary increase. The equation has two parts. Improving either side works in your favour. The nedbank home loans calculator rewards this effort by showing you a more favourable borrowing picture, one that reflects a person who manages their financial life with discipline. Do not ignore the psychological weight of debt. It clouds decision making. Clearing it clarifies your path forward.
Saving for a Larger Deposit
The size of your deposit carries weight before a single application form is signed. The lender measures their exposure against your cash contribution. A larger deposit trims the loan-to-value ratio, which shifts the balance of risk in your favour. The nedbank home loans calculator shows this plainly. A modest increase in your upfront payment reshapes the repayment schedule, lowering the monthly instalment and the total interest over the bond’s life.
- Direct a fixed portion of each salary into a dedicated savings account
- Keep this money separate from everyday spending, so it remains untouched
- Redirect any annual bonus or tax refund towards the deposit fund
Each rand marshalled into your deposit lessens the amount the bank must trust you to repay. The nedbank home loans calculator rewards that sacrifice with a clearer approval picture.
Choosing the Right Bond Structure
Choosing the right bond structure is a strategic decision, not a formality. A fixed rate locks in your monthly instalment, protecting you from interest rate hikes, while a variable rate moves with the prime rate. The nedbank home loans calculator lets you toggle between these scenarios, showing the long term cost of each option. That comparison is the difference between guessing and planning!
Bond structure also affects your approval odds. Lenders assess your risk differently depending on the type you select. A conservative structure may offer a steadier repayment profile, which can work in your favour when the bank weighs up your application.
A few practical steps can help you present a stronger case:
- Keep your employment history stable
- Limit new credit applications in the months before applying
These choices shape the picture the nedbank home loans calculator paints, and that picture guides the bank’s final decision.
Avoiding Common Application Mistakes
Most bond applications are not rejected for dramatic reasons. They fail on the quiet inconsistencies buried in your paperwork. Banks compare every figure you submit, and a single mismatch between your payslip and your stated income can halt the process entirely.
The nedbank home loans calculator lets you model your affordability in advance, but your application file is equally important. I have seen applicants overstate their income by a few thousand rand without checking the figures. That mistake is avoidable. Prepare three months of bank statements, your latest payslip, and verification for any irregular income before you submit.
Avoid these common pitfalls:
- Opening new credit accounts while your application is in review
- Changing your employment status mid process
- Omitting existing loan obligations from your declarations
Each omission undermines your credibility. Use the nedbank home loans calculator to confirm your comfortable repayment range, then present a clean, consistent file. That combination gives the bank a clear picture and improves your odds considerably!
Preparing the Necessary Documentation
Three weeks. That is the average time a bond application spends in the system, and most of it is spent on paperwork. I have seen files stall for days because a single payslip was too faint to read. A clean, complete file changes everything!
Gather these before you open the nedbank home loans calculator:
- Your latest three payslips
- Six months of bank statements
- A certified copy of your ID
Proof of bonus or commission income matters too. Underwriters trust consistency, and your affordability looks stronger when every rand has a source. Present a tidy file and the assessor’s attention stays on your figures, where it belongs.